
SINGAPORE, 20 October 2026 - These are the research findings from the 61st round of the DBS-SKBI Singapore Index of Inflation Expectations (SInDEx) Survey at the Sim Kee Boon Institute for Financial Economics (SKBI), Singapore Management University (SMU), conducted between 11 September and 21 September 2026.
- In the September 2026 survey based on 510 respondents, a large majority, 87.1% of those surveyed, believe that domestic and global economic developments will raise inflation over the next year, down from 87.7% in June 2026. Only 3.9% of respondents think these developments will lower inflation next year, a slight drop from 4.3% in June 2026. The results of this quarterly online survey suggest that many expect inflation to increase in the next year, mainly due to geopolitical instability, conflicts, supply chain disruptions, and global trade policies such as tariffs.
- In September 2026, for the respondents expecting inflation to increase over the next 12 months, the most common reason cited was geopolitical uncertainties and the conflicts involving Hamas and Israel, Ukraine and Russia, and Iran and Israel (59.0%). This is followed by higher trade policy uncertainty, like tariffs (14.2%) and supply chain disruptions (11.3%). Those expecting inflation to decrease only constitute less than 5% of the respondents. In this small sample among those who expect a decline in inflation expectations over the next one year, respondents cited major reasons as a decline in global commodity prices (25.0%), a slowdown in global growth (20.0%), followed by central banks' slowness in reducing interest rates and the resolution of supply chain disruptions (15.0% each).
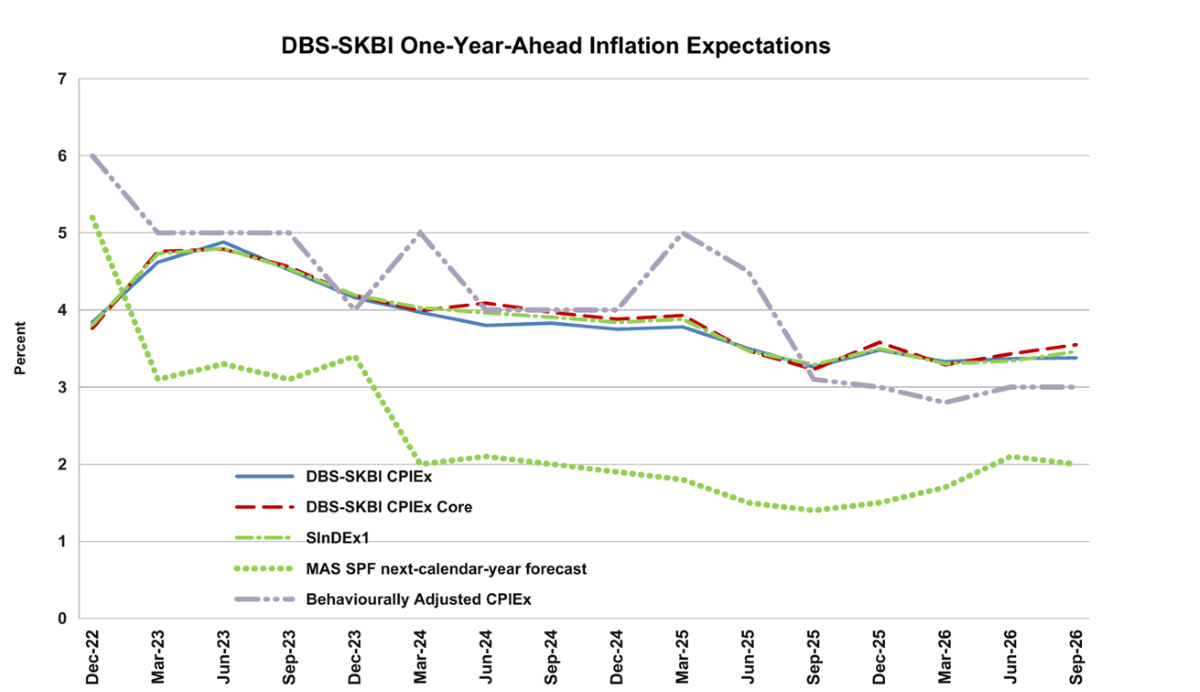
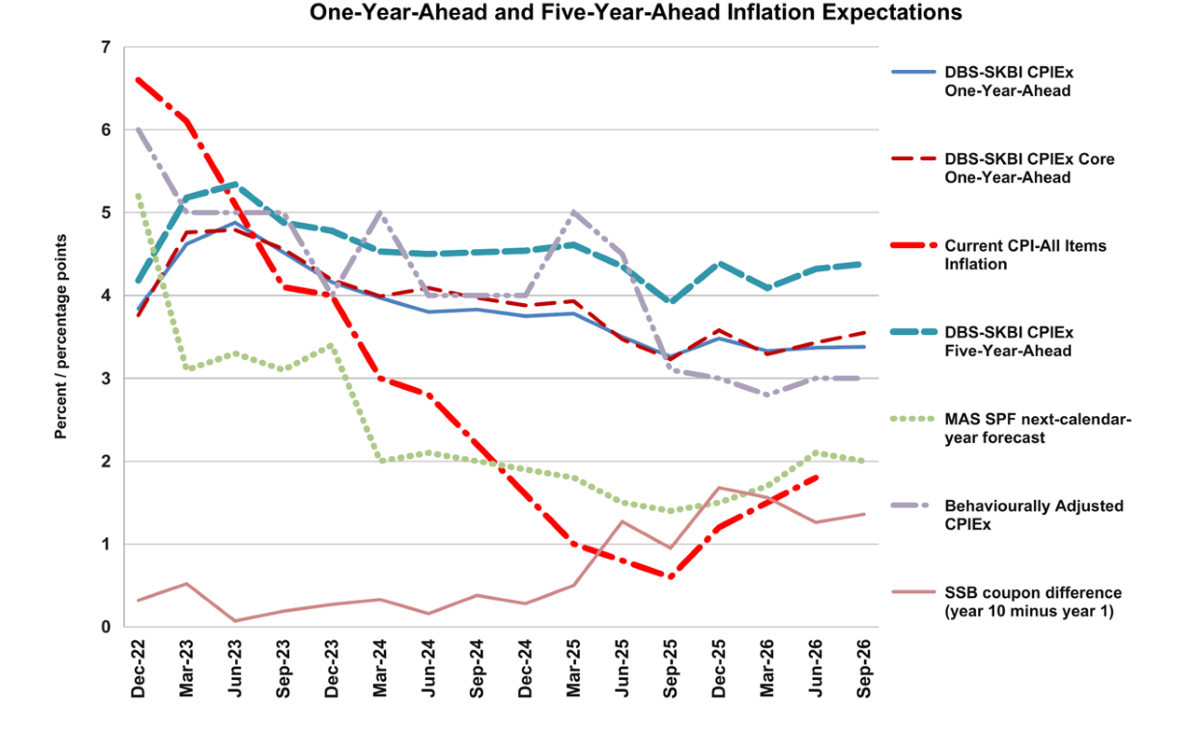
One-year-Ahead headline inflation expectations remained unchanged at 3.4% in September 2026 compared to 3.4% in June 2026 on average. The third quarter One-year-Ahead inflation expectations remained slightly below the average third quarter One-year-Ahead headline inflation expectations of 3.5% recorded since the inception of this index in the third quarter of 2011.
As a comparison, data from the Monetary Authority of Singapore’s Survey of Professional Forecasters (MAS SPF) released in September 2026 showed that the median forecast of the Consumer Price Index (CPI)-All Items inflation for 2026 was 2.1% (2.0% for 2027), while MAS Core Inflation median forecast was 1.9% (2.0 % for 2027) (MAS SPF September 2026, Table A.3 and Table A.5). The latest August 2026 monthly headline or all-items inflation print came at 2.3% year-on-year, while the MAS Core Inflation Measure was 2.2% (MAS-MTI, September 2026). The base year was changed to 2024 with the adjustment of the consumption baskets based on the Household Expenditure Survey 2023. In their first two quarterly reviews of 2025, MAS reduced the rate of appreciation of the Singapore Dollar Nominal Effective Exchange Rate (S$NEER) policy band slightly, implementing two consecutive loosening moves after having kept the policy stance unchanged since October 2022. In April 2026, MAS tightened monetary policy by slightly increasing the slope of the S$NEER policy band, in response to higher projected inflation driven mainly by imported cost pressures. This was followed by a very slight increase in the slope of the policy band in July 2026 (MAS Monetary Policy Statements, July and October 2025, April and July 2026).
- The overall aggregated Consumer Price Index Inflation Expectations, re-combining across components after addressing potential component-wise behavioural biases, inched up to 3.4% in September 2026 from 3.2% in June 2026. One-year-Ahead inflation expectations of major components of CPI held unchanged in some components, namely Food (unchanged at 3.0%), Healthcare (unchanged at 4.0%), Education (unchanged at 3.0%), Household Durables & Services (unchanged at 3.0%) and Recreation, Sport & Culture (unchanged at 3.0%) while there was an increase in Transport (3.8% to 5.0%), Housing & Utilities (3.0% to 3.1%), Clothing and Footwear (2.0% to 2.7%), Information & Communication (2.5% to 3.0%) and Miscellaneous Goods & Services including Personal Care (3.0% to 3.2%). Stability in inflation expectations across some categories, alongside increases in direct oil price-related components like transportation, signals that consumers expect some price increases.
- The survey team also polled free-response overall inflation expectations, after reducing potential behavioural biases by informing respondents of current aggregated economic data. The team found that the One-year-Ahead headline inflation expectations remained unchanged at 3.0% in September 2026 compared to June 2026. These free-response polls help the research team to gauge perceptions of inflation expectations and consumer sentiments in an aggregated sense, with respondents providing their own numerical estimates.
- In the September 2026 survey, continuing since June 2022, we took a more forward-looking approach in analysing the impact of domestic and global economic developments on Singapore’s economic growth and inflation.
- Overall, in response to increasing geopolitical uncertainties and fragilities in the global order, including ongoing and emerging conflicts, and strategic policy uncertainty affecting global trade, Singaporean consumers surveyed in September 2026 expected a slight negative impact of domestic and global developments on the country’s economic growth.
- In addition, Singaporean consumers also opined in the September 2026 survey that over the next 12 months, their overall expenses are expected to increase slightly. Nonetheless, in response to new questions added since the September 2025 survey, respondents believe that their household situation is expected to remain unchanged economically and financially in the next 12 months. They expect business conditions in the next 12 months to slightly worsen compared to last year. Respondents also found that conditions for buying bigger ticket items like household appliances or furniture are expected to slightly worsen in the next 12 months. Over the next five years, however, business situations are expected to be unchanged. The share expecting their household financial situation to worsen over the next year fell from 46.0% in June to 38.6% in September. These median responses indicate stable consumer financial conditions, although there are signs of slightly worse business sentiment in the short run. Consumers expect business conditions in the long run to be more stable.
- In the September 2026 survey, respondents opined that in response to domestic and global economic developments, they expect only a slight increase in the One-year-Ahead headline inflation rate. However, respondents expect a moderate increase in Five-year-Ahead overall inflation expectations. Because of current geopolitical uncertainties, respondents expect one-year-ahead inflation to increase slightly for all components like Food, Transport, Housing & Utilities, Healthcare, Education, Household Durables & Services, Recreation, Sport & Culture, Information & Communication, Clothing & Footwear, and Miscellaneous Goods & Services, corroborating the general findings.
- Alberto Cavallo of Harvard Business School (Cavallo, 2020) and European Central Bank (Kouvavas et al., 2020) highlighted potential biases in CPI calculations with fixed baskets as respondents made substantive changes to their consumption baskets owing mainly to the COVID-19 pandemic. In the September 2026 survey, Singaporean consumers opined that in the next 12 months, they expect no change in the budget share of some components like Education, Clothes & Footwear and Information & Communications, while there is slightly higher budget share for Transport, Housing & Utilities, Healthcare, Household Durables & Services, Food, Recreation, Sport & Culture and Miscellaneous Goods & Services. These expected changes are more recent as the base year was changed to 2024 since 2025 with the consumption baskets taken from the five-yearly Household Expenditure Survey last conducted in 2023.
- Excluding the volatile components of Accommodation and Private Transportation, the One-year-Ahead Consumer Price Index Core Inflation Expectations (CPIEx) increased to 3.6% in September 2026 from 3.4% in June 2026. For a subgroup of the population who owns their accommodation and uses public transport, the One-year-Ahead CPIEx core inflation expectations also inched up to 3.7% in September 2026 from 3.4% in June 2026, corroborating the findings. This sub-sample measurement is potentially more representative of the population experiencing the core inflation, due to their home ownership and public transport ridership.
- Unlike the fixed radio-button response, which might be susceptible to various behavioural biases, the free-response CPIEx Core Inflation Expectations (excluding Accommodation and Private Transportation expenses) remained largely unchanged. After accommodating for potential component-wise behavioural biases and re-combining across components, the CPIEx Core Inflation Expectations (excluding Accommodation and Private Transportation expenses) inched up to 3.3% in September 2026 from 3.2% in June 2026. The free-response core CPIEx Core Inflation Expectations remained unchanged at 3% in September 2026 compared to June 2026. The slightly higher inflation expectations obtained from the fixed response (radio button) compared to the behavioural adjusted free response suggest that there are still some cognitive biases in the fixed response that are partially offset by the behavioural adjusted methods (Clark, Ghosh and Hanes, 2018).
- The One-year-Ahead composite index SInDEx1 that has less weight on more volatile components like Accommodation, Private Road Transport, Food and Energy-related expenses increased to 3.5% in September 2026 from 3.3% in June 2026. It is in line with the third quarter’s average of 3.5% since the inception of the survey in September 2011.
On the household income expectations front, about 7.1% of respondents who provided an income forecast in September 2026 expect more than a 10% reduction in household income next calendar year compared to this year, this has moderately declined compared to 8.5% in the June 2026 survey. The expectation of median household income growth in September 2026 of between 1% and 5% remained unchanged, compared with the June 2026 survey.
Taimur Baig, Chief Economist, DBS Bank Ltd, said: “Price pressures emanating from the Iran war (fuel), AI cycle (electronics), and El Niño (food) notwithstanding, Singapore’s inflation outturn has been modest this year. Concerns about accumulating price shocks are amply illustrated in the DBS-SKBI survey results, although respondents do not see matters worsening from how they were a quarter ago. This was reflected in their one-year inflation expectation responses, which remained stable. The inflation outlook may be characterised by lingering uncertainties, but high policy credibility continues to keep expectations well-anchored.”
Professor Hong Zhang, Keppel Professor in Financial Economics and Director of SKBI at SMU, said: “Trade policy uncertainty has become a more common concern even though near-term headline inflation expectations remain stable. Geopolitical instability remains the main concern, cited by 59.0% of respondents who expect domestic and global developments to raise inflation. The share citing trade policy uncertainty, including tariffs, rose from 9.4% in June to 14.2% in September. It is now the second most cited reason, ahead of supply chain disruptions.”
“For households, the cost of living depends on what they buy. Although One-year-Ahead headline inflation expectations held at 3.4%, expected transport inflation rose from 3.8% to 5.0%, while healthcare expectations remained at 4.0%. Different spending patterns can therefore produce different expected pressures on household budgets. Research shows that consumers draw on price changes in their own grocery purchases when forming aggregate inflation expectations (D’Acunto et al., 2021). Reading the headline alongside these everyday price expectations gives a fuller picture of the pressures households anticipate on their budgets,” Prof Zhang noted.
For the longer horizon, the Five-year-Ahead CPIEx inflation expectations increased to 4.4% in September 2026 compared to 4.3% in June 2026, slightly above the third-quarter average of 4.2% polled since the survey’s inception in September 2011.
The Five-year-Ahead CPIEx core inflation expectations (excluding costs related to Accommodation and Private Transportation) increased to 4.2% in September 2026 compared to 3.8% in June 2026. Overall, the composite Five-year-Ahead SInDEx5 also increased in September 2026 to 4.2% compared to 4.0% in June 2026. In comparison, the third-quarter average value of the composite Five-year-Ahead SInDEx5 is 4.1%, since the survey’s inception in September 2011.
After accommodating for potential behavioural biases, the free-response Five-year-Ahead Headline Inflation Expectations increased from 3.4% in June 2026 to 4.4% in September 2026. Five-year-Ahead Singapore Core Inflation Expectations also increased to 4.0% in September 2026 from 3.6% in June 2026.
Prof Zhang added, “Inflation expectations further ahead matter for household financial planning. Research documents how inflation expectations shape households’ and firms’ economic choices (Weber et al., 2022). Five-year-Ahead core inflation expectations rose from 3.8% to 4.2%, a larger increase than the rise in headline expectations from 4.3% to 4.4%. The stronger rise in longer-term core inflation expectations is worth watching: even when near-term inflation expectations remain stable, expectations about future prices can still shape how households save and spend over a longer horizon.”
Methodology
DBS-SKBI SInDEx survey yields CPIEx Inflation Expectations (estimating headline inflation expectations) and related indices as products of the online quarterly survey of around 500 individuals representing a cross section of Singaporean households. The survey is led by Principal Investigator Professor Hong Zhang, Keppel Professor in Financial Economics at Lee Kong Chian School of Business of Singapore Management University. The online survey, administered by YouGov, helps researchers understand the behaviour and sentiments of decision makers in Singaporean households. DBS Group Research is a co-sponsor and research partner with the Sim Kee Boon Institute for Financial Economics (SKBI) at SMU.
The quarterly DBS-SKBI SInDEx survey has also yielded two composite indices, SInDEx1 and SInDEx5. SInDEx1 and SInDEx5 measure the One-year inflation expectations and the Five-year inflation expectations, respectively. The sampling was done using a quota sample over gender, age and residency status to ensure representativeness of the sample. Employees in some sectors like journalism and marketing were excluded as that might have an effect on their responses to questions on consumption behaviour and expectations.
The DBS-SKBI SInDEx survey was augmented in June 2018, based on a joint research study conducted by SMU researchers in collaboration with MAS and the Behavioural Insights Team, where respondents were polled on their perceptions of components of the Consumer Price Index (CPI) and adjusted for possible behavioural biases prevalent in online surveys.
Based on the recommendations of the joint study, since March 2019 the research team has polled the One-year-Ahead inflation expectations of all of the major components of CPI-All Items inflation. For the September 2026 survey, DBS-SKBI CPIEx One-year-Ahead headline inflation expectations indices remained unchanged from June 2026. The core inflation expectations also increased in September 2026 compared to June 2026. Consistently, the behaviourally adjusted component-wise and recombined inflation expectations held steady or increased slightly in September 2026 compared to June 2026. In free-response answers, compared to June 2026 survey, responses in the September 2026 survey polled for One-year-Ahead Headline and Singapore Core held steady. Overall, the results indicate that medium-term (One-year-Ahead) inflation expectations held steady or increased slightly even after adjusting for behavioural bias prevalent in consumer surveys. However, for the longer term, Five-Year-Ahead headline inflation expectations increased while the Five-Year ahead core inflation expectations increased. Similarly, adjusting for behavioral bias, both the Five-year-ahead headline and core inflation expectations increased in September 2026.
References:
Cavallo, A., 2020, "Inflation with COVID Consumption Baskets." NBER Working Paper Series, No. 27352, June 2020 (Harvard Business School Working Paper, No. 20-124, May 2020). (https://www.hbs.edu/faculty/Pages/item.aspx?num=58253, accessed on July 14, 2020)
Clark, A., A. Ghosh and S. Hanes, 2018, “Inflation Expectations In Singapore:
A Behavioural Approach,” Macroeconomic Review, Vol 17:1, pp. 89-98. https://thedocs.worldbank.org/en/doc/2b672b3b0415d6b66c45b66579db4ef5-0050012026/original/GEP-Jun-2026.pdf
D’Acunto, F., U. Malmendier, J. Ospina and M. Weber, 2021, “Exposure to Grocery Prices and Inflation Expectations,” Journal of Political Economy, 129:5, pp. 1615–1639. https://doi.org/10.1086/713192
Household Expenditure Survey (2023): (https://www.singstat.gov.sg/-/media/files/publications/households/hes20…, accessed on July 17, 2025)
Kouvavas, O., R. Trezzi, M. Eiglsperger, B. Goldhammer and E. Goncalves, 2020, “Consumption patterns and inflation measurement issues during the COVID-19 pandemic,” ECB Economic Bulletin, Issue 7/2020. (https://www.ecb.europa.eu/pub/economic-bulletin/html/eb202007.en.htmlhttps://www.ecb.europa.eu/press/economic-bulletin/focus/2020/html/ecb.ebbox202007_03~e4d32ee4e7.en.html, accessed on October 5, 2026)
MAS Monetary Policy Statement- January 2025, April 2025, April 2026, July 2026 (https://www.mas.gov.sg/news/monetary-policy-statements/2025/mas-monetar…, accessed on Oct 17 2025; https://www.mas.gov.sg/news?date=2025-01-01T00:00:00Z,2025-12-31T23:59:…, accessed Oct 17, 2025, https://www.mas.gov.sg/news/monetary-policy-statements/2026/mas-monetary-policy-statement-14apr26, accessed on April 16, 2026; https://www.mas.gov.sg/news/monetary-policy-statements/2026/mas-monetar…, accessed on October 10, 2026)
MAS Survey of Professional Forecasters (MAS SPF), (https://www.mas.gov.sg/-/media/mas-media-library/monetary-policy/mas-su…, accessed on September 25, 2026)
MAS and MTI, “Consumer Price Developments in August 2026,” released 23 September 2026. https://www.mti.gov.sg/newsroom/consumer-price-developments-in-august-2… (accessed 25 September 2026). SSB October 2026 coupon schedule, issue GX26100Z: https://www.mas.gov.sg/-/media/mas/sgs/sgs-announcements-pdf/ssb-pdf/20… (accessed 5 October 2026).
Weber, M., F. D’Acunto, Y. Gorodnichenko and O. Coibion, 2022, “The Subjective Inflation Expectations of Households and Firms: Measurement, Determinants, and Implications,” Journal of Economic Perspectives, 36:3, pp. 157–184.